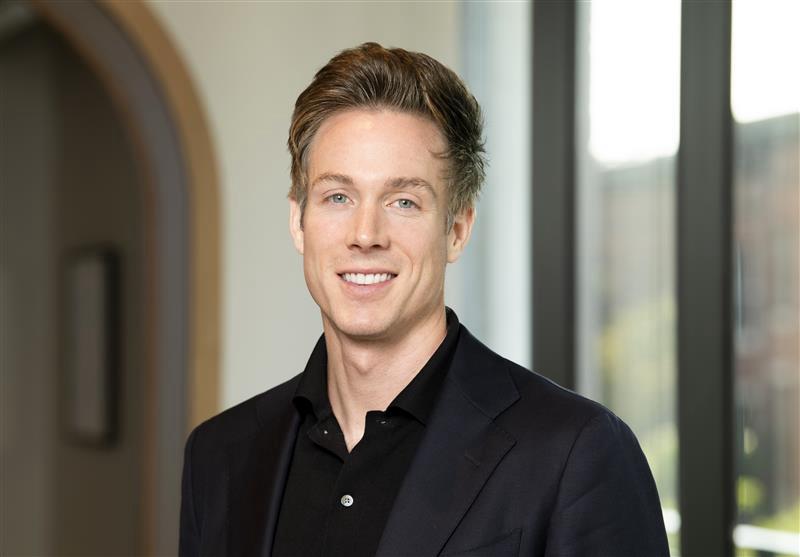
Sam Tidswell-Norrish is a Partner at Access Holdings, where he leads fundraising, investor relations and marketing. He is also the founder of Independent Sponsor News (ISN) and was previously part of the founding team at Motive Partners. We spoke with Sam about how technology and AI are reshaping private equity, the opportunities in the lower middle market and how investment firms can build lasting competitive advantages.
WestGate Partners: You were part of the founding team at Motive Partners and helped build the firm from its inception. What did you learn about building a private equity platform that you don't learn from working at an established firm?
Sam Tidswell-Norrish: As an emerging manager, the journey is long and not without tough moments. To distill it down, I think through the 7 Ps as the areas one must focus on when building a robust and defensible narrative: Product, Performance, People, Place, Process, Purpose and Pipeline. In a smaller firm the talent equation is a journey too, because team members go from generalists working on multiple functions to more singular areas of focus as the firm grows, and attracting great talent early on requires more calories than at a more established brand name.
WGP: You've now moved from Motive Partners, which was focused on financial technology, to Access Holdings and the lower middle market. What has surprised you most about the differences between those two investment environments?
STN: There are many similarities: both are specialized with deep value creation capabilities, both are relatively young in their evolution and both have timed interesting market trends, one with the rise of financial technology and the other with the rise of HALO assets. The difference is that Access Holdings invests exclusively in the lower middle market, in heavier assets that can be improved by technology but not dislocated by it. The deep research we conduct and theses we debate, often for years, are in essential services businesses critical to consumers and businesses, and it is deeply rewarding to work with these critical core economy companies.
WGP: You've argued that the lower middle market remains one of the best places to create alpha. What is it about that part of the market that still allows an investment firm to have an edge when so much capital is chasing private businesses?
STN: The opportunity to buy attractively on the way in and to professionalize the business with experience-driven, tech-enabled playbooks is where the opportunity lies for us. Control investing in the lower middle market is not for the faint-hearted, and it requires a build-and-buy mindset rather than buy-and-build, because you really are taking these companies from small to large very quickly. That mindset is reflected in the types of investment professionals we hire, and why we have built a dedicated 18-person value creation division through what we call the A2C, or Access Acceleration Center.
WGP: Access Holdings' founder Kevin McAllister talks about the firm's "early days as an independent sponsor." What actually happens inside a firm as it transitions from doing deals as an IS to raising a committed fund, and what would you tell an IS today who is trying to make that same leap?
STN: Access did not simply stop being an Independent Sponsor one day and become a fund manager the next; it was a long journey of proving the model investment by investment while building the team, processes and institutional credibility required to manage committed capital. The real transition is from demonstrating that you can complete a good individual deal to demonstrating that you have a repeatable investment product, and my advice to an IS trying to make the leap is not to institutionalize away the attributes that made you successful in the first place, whether entrepreneurial, resourceful or close to management teams. That experience is also why we launched ISN: the Independent Sponsor ecosystem has grown enormously but still lacks consistent news, data, intelligence and connectivity, and we are trying to build some of the infrastructure Access would have valued during its own journey.
WGP: You've described innovation in private equity as happening across origination, portfolio value creation and distribution. Which of those three areas do you think is going to change the most over the next five years?
STN: The world of private markets will look much more quantitative in the future, akin to intraday trading, with companies being managed hour-to-hour versus quarter-to-quarter. Truth be told, all these areas are going to change dramatically, but they all begin with data and automated workflows. The Access operating system is an interconnected quantitative system with four core areas of focus: Capital Management, Research & Origination, Execution and Value Creation, all sitting on top of a data warehouse we built with Snowflake, which allows us to manage our portfolio companies down to the store and SKU level in partnership with our management teams.
WGP: You've said relationships may become more valuable as private equity becomes more data-driven. Why do you think technology will make relationships more important rather than less?
STN: Technology is leveling access to tools and external information, but what it does not level is access to a firm's proprietary knowledge, internal data or relationships. As more firms gain access to similar technology, the differentiation increasingly comes from what only your organization knows, how you apply it and whether people trust you enough to act on it. Somewhat counterintuitively, the democratization of technology will make relationships more valuable: the tools are increasingly available to everyone, but trust, judgment and shared experience are not.
WGP: You served as EVP and CMO at Dun & Bradstreet as a Motive portfolio company. What did the operator seat teach you about how private equity investors and portfolio company executives actually talk past each other, and how did that change how you now show up as a Partner at Access?
STN: I would recommend the opportunity to work in a portfolio company to anyone who can, because it gives you a totally different lens and a much greater level of empathy, which can sometimes be hard to find in our industry. What it also taught me is that portco management teams typically know very little about the underwrite, about how you are marking the asset or about what the GP-level KPIs are for the portco and fund each quarter, which makes it hard for them to drive the right outcomes. At Access we use EOS as a management system connecting the big vision to the quarterly milestones, and all of our portcos use it too, which has been transformational for us.
WGP: Access has increasingly emphasized embedded operating capabilities and technology as part of value creation. What separates a value-creation plan that looks impressive in an IC memo from one that actually changes the trajectory of a portfolio company?
STN: A value-creation plan only matters if it survives the first Monday morning after the investment closes. At Access, the work begins before we invest with a five-year Destination Plan that defines what the business can become and the capabilities it will require, because companies may now need to accomplish in five years what previously took 10 or 15. Most importantly, it must be management's plan too, because if the plan only exists in an IC memo or board presentation, it is not really a plan, and lasting change only happens when the people running the company understand the destination, believe in it and have the support required to reach it.
WGP: Private equity has changed significantly since you helped launch Motive in 2015. What is one change you think has genuinely improved the industry, and one change that has made it worse?
STN: The increased emphasis on genuine operating capability has improved the industry, because financial engineering alone is no longer enough, and firms need to demonstrate how they will help management teams build stronger, more adaptable businesses through better data, technology, talent and execution. The less positive change is that the industry has increasingly equated scale with success, and the pressure to raise more capital and pursue larger transactions can pull firms away from the markets and capabilities that originally gave them an edge. At Access we are clear that the lower middle market is not a temporary stop on the way to larger deals, it is where we believe a focused investor with genuine research and operating capabilities can create differentiated value.
WGP: After helping build Motive, working inside a portfolio company, building OPUS and now helping scale Access, what's one belief about private equity, entrepreneurship or value creation that you've completely changed your mind about?
STN: I am going to cheat slightly on this question, because I have not actually changed my mind: I have always believed that relationships are everything, and every stage of my career has made me more convinced of it. Motive, Dun & Bradstreet, OPUS and now Access have all reinforced the same lesson, that building anything worthwhile is always a team sport, and I have only got this far because people have taken a chance on me, challenged me and supported me when things were difficult. Asking for help is not weakness, and resilience is not about standing alone; it is about knowing who you can lean on and making sure you are there when others lean on you, because relationships remain the ultimate unfair advantage.
Sam can be reached at Access Holdings or on LinkedIn. To follow ISN, click here.